
Step-by-Step Home Loan Application Process in India
A clear, step-by-step walkthrough of the home loan application process in India, from eligibility check to disbursement, and how to avoid common delays.
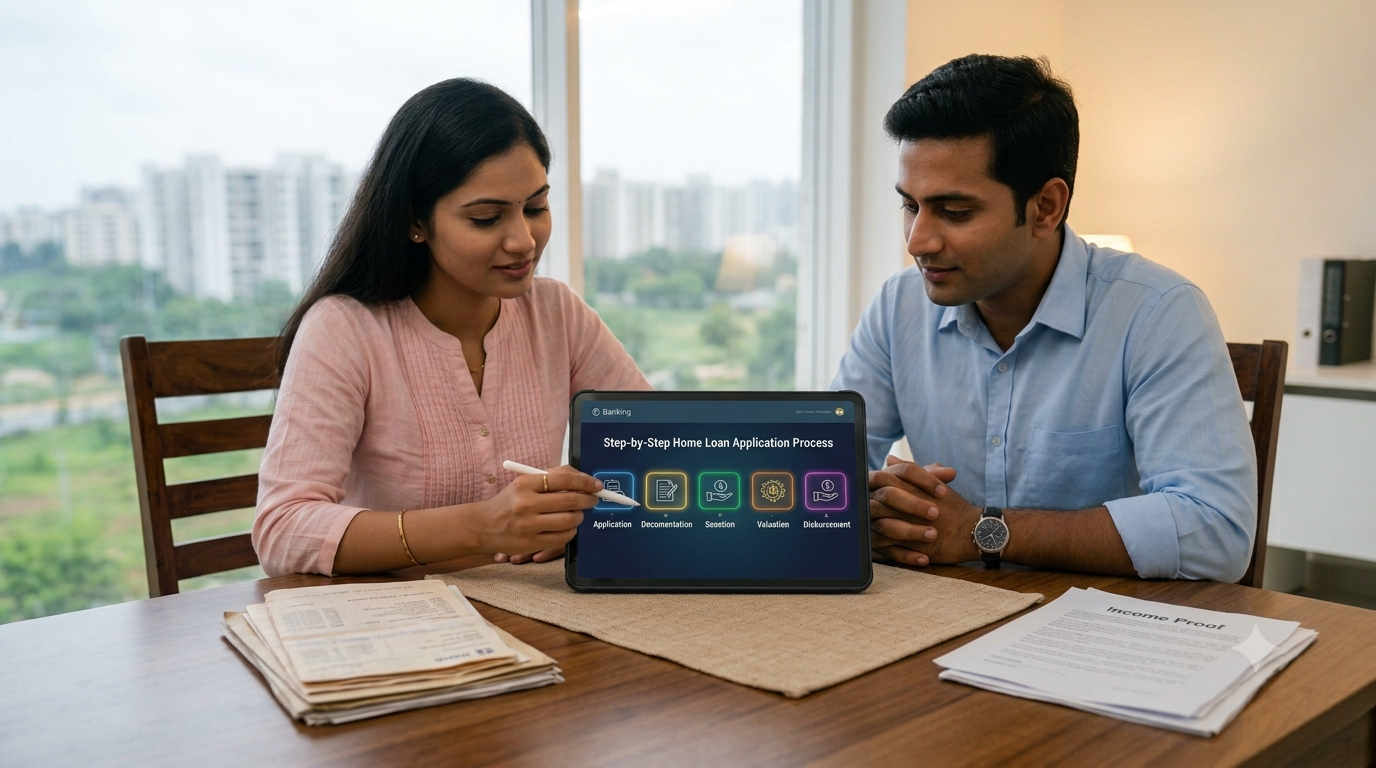
Step 1: Check Eligibility and Compare Lenders
Before filling any form, get a realistic eligibility estimate and compare interest rates, processing fees and loan-to-value ratios across at least three to four lenders. This single step, often skipped in the rush to apply, is what determines whether you end up with a good deal or an average one.
Step 2: Gather and Organise Documents
Collect KYC documents, income proof, bank statements and property papers as per the checklist your chosen lender requires. Applications with a complete, well-organised document set move through underwriting significantly faster than those submitted piecemeal.
Step 3: Submit the Application and Pay Processing Fee
Submit your application along with the processing fee, which is typically 0.25-1% of the loan amount depending on the lender. This triggers the formal underwriting process, including your credit check and income verification.
Step 4: Credit Appraisal and Field Verification
The lender verifies your CIBIL score, cross-checks your income documents, and often conducts a physical or telephonic verification of your residence and workplace. This stage typically takes anywhere from three days to two weeks depending on the lender and how quickly you respond to queries.
Step 5: Property Legal and Technical Verification
In parallel, the lender's empanelled lawyer verifies the property's title chain and legal clarity, while a technical valuer assesses the property's market value and construction quality. Any discrepancy in property documents at this stage is one of the most common reasons for delay.
Step 6: Sanction Letter
Once appraisal and verification are cleared, the lender issues a sanction letter specifying the approved loan amount, interest rate, tenure and conditions. Read this carefully, it is your opportunity to negotiate terms before signing the final loan agreement.
Step 7: Loan Agreement and Disbursement
After signing the loan agreement and submitting original property documents for the lender's custody, funds are disbursed, either fully for a ready property or in tranches linked to construction milestones for an under-construction property.
We Manage the Process End-to-End
Perfect Solutions coordinates directly with the lender's credit, legal and technical teams on your behalf, chasing document requirements and resolving queries quickly, so your file doesn't sit idle in someone's inbox for lack of a single follow-up call.
Common questions
Frequently asked questions
How long does the entire home loan process take?
For a straightforward salaried application with complete documents, sanction typically takes 7-15 days, with disbursement following soon after property document submission. Self-employed or complex cases can take longer.
Can I negotiate terms after receiving the sanction letter?
Yes, to a limited extent. Rate, processing fee waivers, and minor conditions can sometimes be negotiated before you sign the final agreement, especially if you have a competing offer from another lender.
What causes the most delays in home loan processing?
Incomplete documentation, unresponsive employer verification calls, and property title issues (unclear chain of ownership, missing NOCs) are the most common causes of delay.
Want a checklist made for your file?