
Minimum CIBIL Score Required for Home Loan Approval
Find out the minimum CIBIL score banks and NBFCs require for home loan approval in 2026, how it affects your interest rate, and how to fix a low score fast.
What CIBIL Score Do You Actually Need
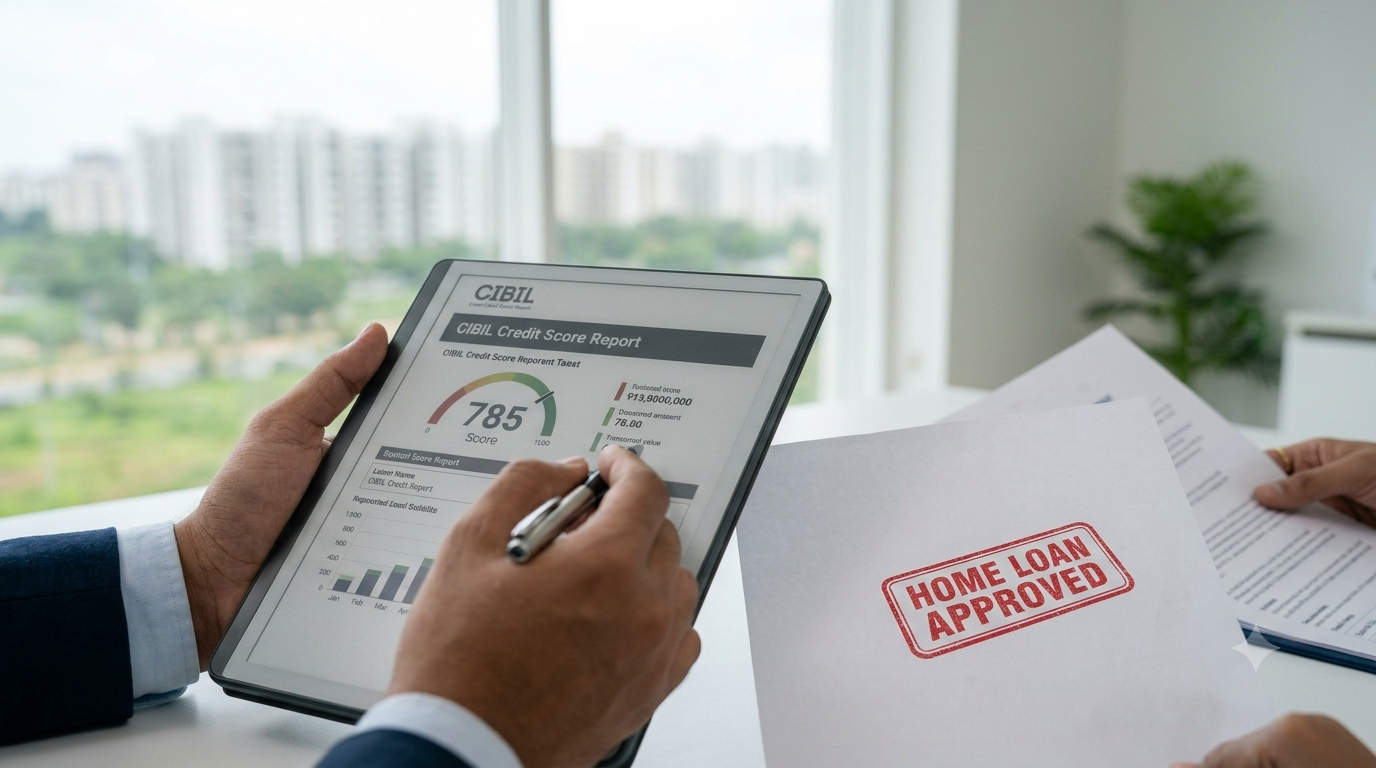
Most banks and housing finance companies in India want to see a CIBIL score of 750 or above before offering their best home loan interest rate. A score between 700 and 749 will usually still get you approved, but often at a slightly higher rate or with additional documentation. Below 700, approval becomes harder and is largely limited to NBFCs that price in the extra risk with a higher rate. Below 650, most mainstream lenders will decline the application outright.
Why Your Score Matters More Than You Think
Your CIBIL score is not just a yes-or-no gate, it directly changes your interest rate. On a ₹50 lakh, 20-year loan, even a 0.5% difference in interest rate can change your total interest outgo by several lakh rupees over the tenure. This is why two people with identical income can be offered very different EMIs purely based on their credit history.
What Actually Brings Your Score Down
The most common score-killers are late credit card payments, running your credit card close to its limit every month, having too many loan enquiries in a short span, and errors in your credit report from a lender who has misreported your account status. Co-signing a loan for a friend or relative who then defaults also silently damages your own score.
How to Fix a Low Score Before You Apply
Pull your credit report from CIBIL, Experian or CRIF Highmark and check for errors first, since incorrect entries are more common than people realise and can be disputed and corrected within 30-45 days. Pay off credit card dues in full rather than the minimum amount, keep utilisation under 30% of your limit, and avoid applying for multiple loans or cards at the same time. A consistent 6-9 month track record of on-time payments can lift a mediocre score meaningfully.
How Perfect Solutions Helps When Your Score Isn't Perfect
Not every lender scores the same file the same way. Our team maps your specific profile against the lenders most likely to approve you at a fair rate, rather than sending your application to everyone and risking further score damage from multiple hard enquiries. If your score genuinely needs repair first, we will tell you honestly and help you build a plan.
Common questions
Frequently asked questions
Can I get a home loan with a CIBIL score below 650?
It is difficult with mainstream banks, but some NBFCs consider applications with scores in the 600-650 range, usually at a higher interest rate and with a co-applicant or additional collateral.
How long does it take to improve a CIBIL score?
A meaningful improvement typically takes 4-9 months of consistent on-time payments and low credit utilisation, though correcting a factual error on your report can improve your score within 30-45 days.
Does checking my own CIBIL score reduce it?
No. Checking your own score is a soft enquiry and does not affect your score. Only hard enquiries made by lenders when you apply for credit impact your score.
Not sure where you stand?